Landlord Tax Hits 47%: What the 2% Rise Really Costs You
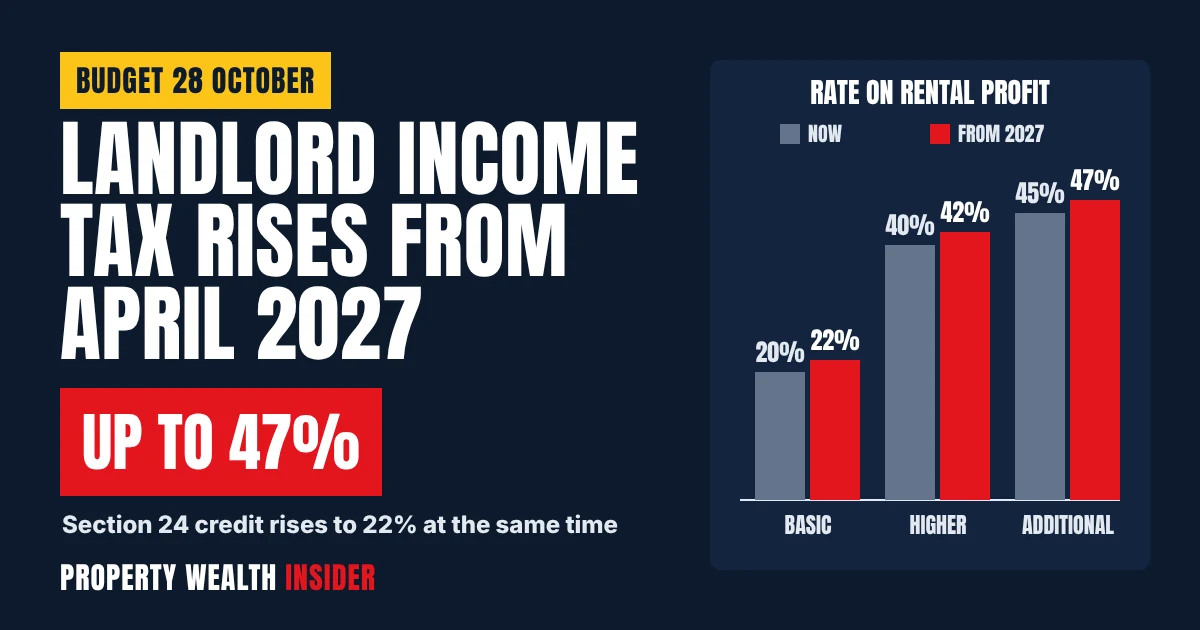
Landlords who own property in their own names have 18 months left before income tax on their rental profits goes up by 2 percentage points. From 6 April 2027, property income gets its own tax rates of 22%, 42% and 47%, and that change is already law.
With Chancellor John Healey’s first Budget due on 28 October 2026, landlords are bracing for more change, yet this rise is already law. The real question is what it costs you, and whether rents will move to cover it.
So how much will it actually cost you? Less than many landlords fear, and less again if you have a mortgage. Below we explain how the new rates interact with Section 24, give worked examples in pounds, and include a calculator so you can run your own figures.
Key facts
- From 6 April 2027, property income is taxed at 22% / 42% / 47%. Today it is taxed at 20% / 40% / 45%.
- Section 24 mortgage interest relief goes up to 22% at the same time, so it covers more of the rise.
- The new rates are in Finance Act 2026. They apply to individual landlords in England, Wales and Northern Ireland. Scotland sets its own rates.
- HMRC estimates that about 2.4 million landlords will be affected.
- For most landlords, the extra tax is roughly 2% of rental profit after mortgage interest.
- The next Budget is on 28 October 2026.
What changes in April 2027
The government announced the change at Budget 2025 on 26 November 2025. Rental profits were previously taxed at the same rates as wages. From the 2027/28 tax year they get their own set of rates. Section 7 of Finance Act 2026 sets the property basic rate at 22%, the property higher rate at 42% and the property additional rate at 47%.
Savings income goes up by the same 2 points from April 2027. Dividend tax rates already rose in April 2026. According to the House of Commons Library, the three measures together are forecast to raise about £2.3 billion a year from 2028/29.
The order in which allowances are used is changing too. From April 2027, your personal allowance and other reliefs will be set against wages, pension and trading income first. Property income will sit on top. In practice, that means your rental profit is taxed at your highest band.
| Band (England, Wales, NI) | Taxable income | Rate on rent now (2026/27) | Property rate from 6 April 2027 |
|---|---|---|---|
| Personal allowance | Up to £12,570 | 0% | 0% |
| Basic | £12,571 to £50,270 | 20% | 22% |
| Higher | £50,271 to £125,140 | 40% | 42% |
| Additional | Over £125,140 | 45% | 47% |
| Section 24 finance cost credit | On mortgage interest | 20% | 22% |
Your personal allowance shrinks by £1 for every £2 of income over £100,000. That creates an effective 60% band (62% on property income from 2027) between £100,000 and £125,140.
How Section 24 changes too
Since Section 24 came in, individual landlords have not been able to deduct mortgage interest from their rental income. Instead, they get a tax credit at the basic rate. HMRC’s guidance says the credit is 20% of whichever is lowest out of three amounts: your finance costs, your property profits, or your income above the personal allowance. Any finance costs you cannot use are carried forward.
HMRC’s technical note confirms that the credit will be given “at the property basic rate” from 2027/28. In other words, it rises from 20% to 22%.
The useful shortcut: tax on your rental profit goes up by 2 points, and your mortgage interest credit also goes up by 2 points. As long as your interest is fully relieved, the extra tax is roughly 2% × (taxable rental profit − mortgage interest). That holds whether you are a basic, higher or additional rate taxpayer. Landlords with large mortgages are hit least.
That doesn’t mean higher-rate landlords escape lightly. They still lose 42% of every extra pound of rent to tax. So if they want to recover the extra tax through higher rent, they need to raise rents by much more than the tax itself.
Worked examples: what it costs in pounds
All examples use 2026/27 thresholds for both years so you can see the effect of the rate change on its own. “Expenses” means allowable costs other than mortgage interest.
| Landlord | Rental profit before interest | Mortgage interest | Tax on rent now | From April 2027 | Extra a year | Rent rise to stay whole |
|---|---|---|---|---|---|---|
| A: one flat, unmortgaged, £25,000 salary | £10,000 | £0 | £2,000 | £2,200 | £200 | £256 a year |
| B: higher-rate employee, £45,000 salary | £15,000 | £7,000 | £3,546 | £3,706 | £160 | £276 a year |
| C: two mortgaged houses, £40,000 salary | £25,000 | £15,000 | £4,946 | £5,146 | £200 | £345 a year |
| D: full-time landlord, no other income | £75,000 | £30,000 | £11,432 | £12,081 | £649 | £1,118 a year |
| E: £80,000 salary, unmortgaged portfolio | £50,000 | £0 | £25,271 | £26,271 | £1,000 | £1,887 a year |
Landlord B in detail. The £45,000 salary uses up the personal allowance and all but £5,270 of the basic rate band. Today, the £15,000 profit is taxed as £5,270 at 20% (£1,054) plus £9,730 at 40% (£3,892), which comes to £4,946. Take off a £1,400 Section 24 credit and the tax is £3,546. From April 2027 it becomes £1,159 + £4,087 − £1,540, which is £3,706. That is £160 a year more, or about £13 a month.
Landlord E is hit hardest because there is no mortgage interest to soften the rise. Their total income of £130,000 has also wiped out the personal allowance. That loss is counted in the tax on rent shown above, and their marginal rate on rent goes from 45% to 47%. To stay whole, they would need almost £1,900 more rent a year.
Calculator: your extra tax from April 2027
Enter your figures for property you own personally (not through a limited company). The calculator works out the tax on your rental profit under today’s rates and under the 2027 property rates. It shows the rise per year and per month, and the extra rent you would need to stay whole after tax.
Property income tax rise calculator
Guide only, not tax advice. Uses 2026/27 England, Wales and NI thresholds for both years (personal allowance £12,570, tapered above £100,000). It assumes no brought-forward losses or finance costs and no savings or dividend income. It does not cover Scottish taxpayers or limited companies. Check your own position with an accountant.
Will rents rise to cover it?
For a typical mortgaged landlord, recovering the 2027 rise needs a few hundred pounds a year in extra rent across the whole portfolio. That is a small part of any rent increase, but it is not nothing. It also adds to other costs landlords face, such as compliance with the Renters’ Rights Act.
Scotland, Wales and Northern Ireland
England and Northern Ireland: the 22%, 42% and 47% rates apply from 6 April 2027.
Wales: the House of Commons Library says the new rates apply in Wales. However, section 8 of Finance Act 2026 lets the Senedd set Welsh property rates instead. That power can start no earlier than 2027/28, on a date the Treasury appoints. If you are a Welsh taxpayer, look out for announcements in the Welsh budget.
Scotland: GOV.UK describes the new figures as “rUK rates, not applicable to Scotland”. The same section gives the Scottish Parliament the power to set Scottish property rates. Scottish taxpayers should not use the calculator above.
Limited companies pay corporation tax, not income tax, so this change does not affect them. Property held in a company is outside the measure.
What to do before April 2027
- Run your numbers. Use the calculator for each year you expect. Most mortgaged landlords will find the rise is a few hundred pounds, not thousands.
- Check your band position. From April 2027, rental profit sits on top of your other income. Landlords whose income is close to £50,270, £100,000 or £125,140 should look closely at their marginal rate.
- Claim every allowable expense. Each £1 of expenses you claim saves 22p, 42p or 47p from 2027.
- Review ownership with an adviser. Splitting ownership with a spouse who pays a lower rate, or moving to a company, can change your tax bill. But transfers can trigger capital gains tax and stamp duty, so get professional advice first.
- Plan any rent review properly. Work out the gross-up figure from the calculator and compare it with local market rents. Use the correct legal process and notice for any rent increase.
- Watch the 28 October Budget. The 2027 rates are already law. The Budget could still change thresholds, reliefs or other landlord taxes, and we will update this article if it does.
- Total rent received, expenses and mortgage interest for 2025/26 confirmed
- Carried-forward finance costs from earlier years noted
- Expected other income for 2027/28 estimated
- Extra tax worked out with the calculator
- Ownership split and company options discussed with an accountant
- Rent review timetable and notice process checked
- Scottish or Welsh taxpayer status checked
FAQ
When does the 22% property income tax rate start?
It starts on 6 April 2027, at the beginning of the 2027/28 tax year. Your first self assessment return using the new rates will be for 2027/28.
Does Section 24 relief go up to 22%?
Yes. HMRC’s technical note says finance cost relief will be given at the property basic rate from 2027/28, which is 22%. It is still capped at the lowest of your finance costs, property profits and income above the personal allowance.
Do limited company landlords pay the new rates?
No. The new rates apply to income tax on property income, so they affect landlords who own property personally or in a partnership. Companies pay corporation tax. If you take money out of a company as dividends, though, dividend tax rates went up in April 2026.
Will the property tax rise apply in Scotland?
No. The 22%, 42% and 47% rates are not for Scotland. Finance Act 2026 gives the Scottish Parliament the power to set its own property income rates.
How much extra tax will I pay on my rental income?
For most landlords whose mortgage interest is fully relieved, it is roughly 2% of your taxable rental profit minus your mortgage interest. On £20,000 of profit with £8,000 of interest, that is about £240 a year. Use the calculator above for your exact figure.
Could the 28 October 2026 Budget change this?
The rates are already in Finance Act 2026. Any change would need new legislation. Nothing has been announced, so plan on the basis of the current law.
Sources
- Finance Act 2026, section 7: property rates of income tax for 2027-28 (legislation.gov.uk)
- Finance Act 2026, section 8: Scottish and Welsh property rates (legislation.gov.uk)
- HMRC: Income Tax changes to tax rates for property, savings and dividend income (GOV.UK)
- HMRC technical note: change to tax rates for property, savings and dividend income (GOV.UK)
- Changes to tax rates for property, savings and dividend income (GOV.UK)
- HMRC: tax relief for residential landlords, how it is worked out (GOV.UK)
- Income Tax rates and bands (GOV.UK)
- Chancellor’s letter to the Treasury Committee confirming the 28 October 2026 Budget (GOV.UK)
- House of Commons Library: Budget 2025 income tax rates on property, savings and dividends
This article is news and general guidance only. It is not financial, legal or tax advice.