Sell or Keep Your Buy-to-Let? Free Calculator as Tax Hits 49%
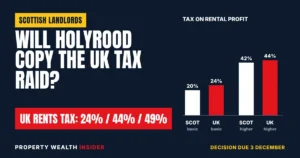
Should you sell your buy-to-let or hang on to it? It is the question landlords ask more than any other, and the Budget on 28 October has made it impossible to put off. From 6 April 2027, rental profits in England, Wales and Northern Ireland will be taxed at 24%, 44% or 49%, four points higher than today.
At the same time capital gains tax on a sale was left alone at 18% and 24%, Bank Rate went up to 4% on 5 November, and the Renters’ Rights Act has changed how you get a property back to sell it. Each of those pulls the sums in a different direction.
So we built a calculator that does the whole job. Put in what you paid, your stamp duty and legal fees, any improvements, your mortgage, rent and running costs, and it works out your capital gains tax bill today, the cash you would actually walk away with, and how that compares with keeping the property for the next 5, 10 or 20 years.
Key facts
- From 6 April 2027, rental profits are taxed at 24%, 44% or 49% in England, Wales and Northern Ireland, up from 20%, 40% and 45%.
- The Section 24 tax credit on mortgage interest rises from 20% to 24% on the same date.
- Capital gains tax on a buy-to-let is unchanged: 18% within your basic-rate band, 24% above it, after a £3,000 tax-free allowance each.
- You can deduct stamp duty, solicitor and estate agent fees and the cost of improvements from your gain, but not decorating or repairs. CGT must be reported and paid within 60 days of completion.
- To sell with vacant possession in England you need Ground 1A: 4 months’ notice, not in the first 12 months of a tenancy, then no re-letting for 12 months, with fines up to £40,000.
- The UK average house price was £273,037 in August 2026, up 3.3% a year over the last decade (UK House Price Index).
The keep-or-sell calculator
Every box starts with an example – a property bought for £180,000 and now worth £275,000 – so you can see how it works before you put your own figures in. Results update as you type. Have your completion statement, mortgage statement and last tax return to hand.
Keep or sell your buy-to-let?
Year-by-year breakdown over 10 years
Not sure how prices have moved in your area? Growth is the number that swings the answer most. Our house price data tool shows official figures for every local authority back to 1995, so you can plug in a growth rate based on your own patch rather than a national guess.
How the calculator works – and what it leaves out
The calculator compares two futures side by side, using the same tax rules for both.
- Sell now. It takes the sale price, knocks off estate agent and legal fees, any early repayment charge and your mortgage, then works out capital gains tax. What is left is the cash you would bank. It then grows that cash at the after-tax return you choose.
- Keep. Each year it takes the rent (less empty weeks), letting fees and running costs, your mortgage interest (and capital, if it is a repayment loan) and income tax on the rent under the Section 24 rules. Year 1 blends today’s rates with the new April 2027 rates; every later year uses 24%, 44% and 49%. The spare cash each year earns the same return as the sale money would.
- The finish line. At the end of the period it assumes you sell at the projected value, clear the mortgage and pay CGT, and adds that to the cash the property threw off along the way. That is your wealth if you keep.
- Break-even growth is the yearly house price rise at which keeping and selling come out exactly level. If you do not believe your area will beat it, selling wins.
- Return on your equity treats the cash you could take out today as an investment and asks what yearly return the property delivers on it. Compare it with the return you put in for the sale money.
What it does not cover: Scottish income tax rates (Scotland and Wales are being given powers to set their own property rates – see our report on the Scottish decision), rental losses or unused finance costs carried forward, inheritance tax, and any future changes to tax rules. All figures are in cash terms, not adjusted for inflation. It is a decision aid, not advice.
Why April 2027 changes the maths
The 2025 Budget created separate income tax rates for property income for the first time, set two points above the normal rates from April 2027. The 2026 Budget then added two more points on top. The Treasury’s Budget document confirms that from 2027/28 the property basic rate will be 24%, the higher rate 44% and the additional rate 49%, across England, Wales and Northern Ireland.
| 2026/27 (now) | 2027/28 as planned at Budget 2025 | 2027/28 after Budget 2026 | |
|---|---|---|---|
| Basic rate on rental profit | 20% | 22% | 24% |
| Higher rate on rental profit | 40% | 42% | 44% |
| Additional rate on rental profit | 45% | 47% | 49% |
| Mortgage interest tax credit (Section 24) | 20% | 22% | 24% |
Two other changes from the same date matter. Your personal allowance will be set against wages, pensions and trading income first, so more of your rent is likely to land in a taxed band. And the tax on savings interest rises to the same 24%, 44% and 49% across the whole UK – so "sell up and put it in the bank" is also being taxed harder, unless the money goes into an ISA or pension.
Section 24: why landlords with mortgages feel it most
Individual landlords cannot deduct mortgage interest from their rent. Instead they are taxed on the profit before interest and get a tax credit worth a flat basic-rate percentage of the interest – 20% today, 24% from April 2027. A higher-rate landlord therefore pays 44% on the profit but gets only 24% back on the interest.
Take £10,000 of rental profit before interest and £6,000 of mortgage interest. The real profit is £4,000. A higher-rate landlord pays £2,800 in tax today – 70% of what is really left – rising to £2,960, or 74%, from April 2027. With £8,000 of interest, the tax bill (£2,480) is bigger than the real profit (£2,000).
Oddly, the landlords hit hardest in cash terms by the April 2027 rise are those with little or no mortgage, because the bigger credit softens the blow for borrowers. In our worked example below, the rise costs the mortgaged owner £128 a year, but the same property owned outright pays £408 a year more.
Capital gains tax: what selling really costs
When you sell a property that is not your home, you pay capital gains tax on the profit. For 2026/27 the rates are 18% on the part of the gain that fits inside your unused basic-rate band and 24% on the rest, after a £3,000 tax-free allowance. The Budget left CGT alone despite weeks of speculation: HMRC’s rates table confirms the same 18%, 24% and £3,000 allowance for 2027/28.
Your taxable income for the year – including the rent – decides how much of the gain falls at 18%. Most landlords with a job or pension pay 24% on most of it. Joint owners each get their own £3,000 allowance and their own basic-rate band, which is why the calculator lets you split the property 50:50 with a spouse. Calls from landlord groups to strip inflation out of gains were not taken up.
What you can deduct from the gain
- What you paid for the property.
- Buying costs: stamp duty, solicitor’s fees, survey fees.
- Improvements that added to the property, such as an extension or loft conversion. Normal maintenance, such as decorating, does not count.
- Selling costs: estate agent’s and solicitor’s fees.
- Private residence relief if you once lived there: relief for the years it was your home, plus the last 9 months you owned it even if you had moved out. Letting relief now only applies if you lived there at the same time as your tenants.
Keep the paperwork. Your completion statement from the purchase shows the price, stamp duty and legal fees; invoices prove improvement work.
A worked CGT bill
| £ | |
|---|---|
| Sale price | £275,000 |
| Less purchase price | -£180,000 |
| Less buying costs (stamp duty, legal, survey) | -£4,500 |
| Less extension | -£10,000 |
| Less selling costs (1.5% agent fee + £1,800 legal and EPC) | -£5,925 |
| Gain | £74,575 |
| Less annual exempt amount | -£3,000 |
| Taxable gain | £71,575 |
| CGT at 24% (owner’s income plus rent already above the basic-rate band) | £17,178 |
| Same property owned 50:50 with a spouse earning £30,000 | £15,537 |
Owning jointly saves this couple £1,641, because the second £3,000 allowance and the spouse’s unused basic-rate band come into play. Transfers between spouses or civil partners who live together do not trigger CGT, but the gift has to be real – they own that share and get that share of the money – and your lender has to agree. Take advice before you move anything.
The 60-day rule. When you sell a UK residential property at a gain, you must report it and pay the CGT within 60 days of completion, through HMRC’s online CGT on UK property service. Do not wait for your tax return. Set the money aside on completion day.
Every cost of selling, in one table
Selling is not just CGT. These are the costs to put into the calculator, and whether they reduce your gain.
| Cost | How it is charged | Reduces your CGT gain? |
|---|---|---|
| Estate agent | Usually a % of the sale price plus VAT – get at least three quotes | Yes |
| Conveyancing solicitor | Fixed fee plus VAT and searches | Yes |
| Energy Performance Certificate | Needed before marketing if yours has expired | Usually, as a cost of selling |
| Early repayment charge | % of the mortgage balance if you are still in a fixed or discounted deal | Ask your accountant |
| Lost rent | Empty months while you sell, or the rent you give up once the tenant leaves | No – it is income, not a cost of the sale |
| Tenanted-sale discount | Investor buyers may pay less than owner-occupiers | No – it simply lowers the sale price |
| Decorating to sell | Freshening up before photos | No – HMRC treats decorating as maintenance |
| Capital gains tax | 18% / 24% after the £3,000 allowance, within 60 days | – |
Selling with tenants: the Renters’ Rights Act rules
Since 1 May 2026, landlords in England can no longer use Section 21. To get a property back empty to sell it, you use a new mandatory ground, Ground 1A, under a Section 8 notice.
- You must give 4 months’ notice before you can apply to court.
- You cannot use it in the first 12 months of a tenancy. You can serve notice during that time, but it cannot expire before the 12 months are up.
- Once you rely on Ground 1A you cannot re-let or market the property to let for 12 months from the date given in the notice – roughly 16 months from serving it. If the sale falls through, the property sits empty or you sell for less.
- Breaking the rule can bring a council fine of up to £40,000 instead of prosecution.
The alternative is to sell with the tenant still in place to another landlord. The tenancy carries on, the rent keeps coming in until completion and there is no re-let ban, but fewer buyers are looking for tenanted homes and some will want a discount. If your tenant is a good one, ask whether they want to buy. Rules in Wales, Scotland and Northern Ireland are different.
What 30 years of house prices say about holding
Growth is the assumption that matters most. The official UK House Price Index shows the average UK home rose from £54,215 in August 1996 to £273,037 in August 2026 – but with a 19% fall from the 2007 peak to the 2009 low, and only 2.8% growth in total between September 2022 and August 2026.
| Period to August 2026 | Average price at start | Total rise | Average rise a year |
|---|---|---|---|
| 5 years | £238,403 | 14.5% | 2.75% |
| 10 years | £198,186 | 37.8% | 3.26% |
| 20 years | £158,476 | 72.3% | 2.76% |
| 30 years | £54,215 | 403.6% | 5.54% |
Where you own matters as much as when. Over the last ten years, average prices rose about 3.0% a year in England, 3.9% in Scotland, 4.6% in Wales and 5.5% in Northern Ireland – but only 0.9% a year in London. A London landlord who plugs in 3% is likely being too optimistic. Use our local house price data to check your own area.
The near-term picture is cautious. Lloyds’ index showed prices down 1.2% on the year in October, and Savills expects a 1.5% fall in 2027. The official ONS figure for August was a rise of 0.9% on the year. That is why the calculator shows a break-even growth rate rather than a single verdict: you can see how much growth you need, then judge whether your area is likely to deliver it.
Worked example: keep or sell a £275,000 buy-to-let
Take a landlord – call her Sarah – who bought a two-bed for £180,000, paid £4,500 in stamp duty and fees, and later spent £10,000 on an extension. It is now worth £275,000, close to the UK average. She has a £140,000 interest-only mortgage at 5%, charges £1,250 a month, pays her agent 12% and spends £2,500 a year on everything else. She earns £45,000 from her job. These are the calculator’s default figures.
If she sells today, she walks away with £111,897 after the mortgage, £5,925 of selling costs and a £17,178 CGT bill.
If she keeps it, the property leaves her about £1,577 a year after every cost and tax in 2027/28 – roughly £131 a month. Her tax on the rent that year is £1,857, which is 54% of the £3,435 actually left after interest. That is Section 24 at work.
Over ten years, with prices rising 3% a year and the sale money earning 4% a year after tax elsewhere, keeping leaves her with £206,844 against £165,635 – £41,209 ahead. Her equity earns about 6.5% a year in the property. But the margin is thinner than it looks: prices only have to grow by less than 1.4% a year for selling to win.
| Scenario (10 years) | Cash if sold now | Wealth if kept | Wealth if sold now | Better option | Break-even growth |
|---|---|---|---|---|---|
| Base case (3% growth, 5% mortgage, 4% elsewhere) | £111,897 | £206,844 | £165,635 | Keep +£41,209 | 1.4% |
| House prices grow 1% a year | £111,897 | £157,581 | £165,635 | Sell +£8,054 | 1.4% |
| House prices flat for 10 years | £111,897 | £136,043 | £165,635 | Sell +£29,592 | 1.4% |
| Mortgage rate rises to 6% | £111,897 | £194,036 | £165,635 | Keep +£28,401 | 1.9% |
| Sale cash earns 6% a year elsewhere | £111,897 | £208,955 | £200,390 | Keep +£8,564 | 2.7% |
| Owned 50:50 with spouse earning £30,000 | £113,538 | £221,867 | £168,064 | Keep +£53,803 | 0.8% |
| Owner earns £120,000 elsewhere | £111,897 | £178,168 | £165,635 | Keep +£12,533 | 2.5% |
| No mortgage | £251,897 | £410,882 | £372,869 | Keep +£38,013 | 1.5% |
Three lessons jump out. Growth is everything: at 1% a year Sarah should sell; at 3% she should keep. A higher mortgage rate hurts her cash flow far more than her ten-year result, because the property’s value does the heavy lifting. And owning jointly with a lower-earning spouse improves both sides of the sum – less tax on the rent and less CGT on the sale.
Signs it may pay to sell – and to keep
Signs selling may make sense
- The property costs you money each month after the April 2027 tax rise.
- The break-even growth rate is higher than your area has managed over the past decade.
- A big bill is coming: EPC upgrades, a roof, cladding or major repairs.
- You are a higher-rate taxpayer with a large mortgage, so Section 24 takes most of the profit.
- You need the money, or managing tenants no longer suits your life.
Signs keeping may make sense
- Your equity earns more in the property than you could get elsewhere after tax.
- Rent comfortably covers the mortgage, costs and tax, with room for rate rises.
- Your area has a long record of steady growth and strong tenant demand.
- You plan to hold for the long term: there is no CGT on death, although inheritance tax may apply.
- You have a good tenant, a low-maintenance property and no need for the cash.
Options between keeping and selling
- Sell one, keep the rest. If you own several properties, sell the one with the weakest yield or biggest upcoming bill. Spreading sales across tax years uses a fresh £3,000 allowance and basic-rate band each year.
- Cut the debt. If Section 24 is the problem, paying down the mortgage on the best property – perhaps with money from selling the worst – reduces the interest that is taxed but only part-relieved.
- Share ownership with your spouse. Transfers between spouses and civil partners living together are free of CGT, and splitting income and gains can lower both bills. It must be a genuine transfer, and your lender must agree.
- Sell to an investor or your tenant. Selling tenanted avoids Ground 1A, keeps the rent flowing until completion and removes the risk of a 12-month re-let ban.
- Hold for life. There is no CGT when someone dies, and whoever inherits is treated as buying at the value on the date of death. Inheritance tax may be due on the estate, so this is a family planning decision, not just a tax trick.
- Move into a company. Transferring a property you own to a company you control is treated as a sale at market value for CGT, and the company pays stamp duty on at least the market value as well. It rarely pays for a single property without specialist advice.
What to do now: step by step
- Gather the numbers. Your purchase completion statement, invoices for improvements, latest mortgage statement (including any early repayment charge), a year of rent and costs, and your other income.
- Get a realistic value. Ask two or three local agents, and check recent sold prices for similar homes nearby.
- Run the calculator three times, with low, middle and high growth – for example 0%, 1.5% and 3% – and over the period you actually intend to hold.
- Check your tenancy dates. If you want to sell empty in England, work out when Ground 1A can be used and how long the 12-month re-let ban would last.
- Talk to a tax adviser before transferring shares to a spouse, changing ownership or timing a sale around a low-income tax year.
- If you sell, set aside the CGT on completion day and diarise the 60-day reporting deadline.
- Purchase price, stamp duty and buying fees found on completion statement
- Improvement invoices collected (extensions, conversions – not repairs)
- Two or three agent valuations, plus recent local sold prices
- Mortgage balance, rate, end of fixed deal and early repayment charge checked
- Rent, letting fees, running costs and empty weeks totalled for the last 12 months
- Your income (and your partner’s) for this tax year and next estimated
- Calculator run at 0%, 1.5% and 3% growth
- Tenancy start date checked against the 12-month protected period
- Tax adviser consulted on ownership and timing
- CGT set aside and 60-day deadline in the diary
FAQ
Do I have to pay capital gains tax when I sell a buy-to-let?
Yes, if you make a gain after costs and your £3,000 annual allowance. For 2026/27 the rates are 18% on the part of the gain within your unused basic-rate band and 24% on the rest. If the property was once your home, private residence relief can reduce or remove the bill.
Can I deduct stamp duty and legal fees from my capital gain?
Yes. Stamp duty, solicitor’s and surveyor’s fees when you bought, estate agent and solicitor’s fees when you sell, and the cost of improvements such as an extension all reduce the gain. Repairs and decorating do not.
Should I sell my buy-to-let before April 2027?
Not for CGT reasons. The April 2027 change raises tax on rent, not on gains: CGT stays at 18% and 24% with a £3,000 allowance in 2027/28 too. The rise only affects the rent you would collect by keeping the property, which is exactly what the calculator weighs up. For CGT, what matters more is your income in the tax year you sell, because that decides how much of the gain is taxed at 18% rather than 24%.
How long do I have to pay capital gains tax after selling a rental property?
You must report the sale and pay any CGT within 60 days of completion, using HMRC’s online service for CGT on UK property. This is separate from your Self Assessment return.
Can I sell my rental property with tenants in it?
Yes. The tenancy simply continues with the new owner. You will mostly be selling to other landlords, which can mean a smaller pool of buyers, but there is no notice period and no 12-month re-let ban.
Is it better to keep a buy-to-let until I die?
There is no CGT on death, and whoever inherits the property is treated as buying it at its value on the date of death, wiping out the gain. But the property counts towards your estate for inheritance tax, so the right answer depends on the size of your estate and your family’s plans.
- HM Treasury: Budget 2026 (28 October 2026)
- HMRC: Budget 2026 overview of tax legislation and rates – Annex A
- HMRC: Income Tax – changes to tax rates for property and savings income (Budget 2026)
- HMRC: Change to tax rates for property, savings and dividend income – technical note (Budget 2025)
- HMRC: Changes to tax rates for property, savings and dividend income (Personal Allowance ordering)
- Saffery: Autumn Budget 2026 for individuals (finance cost relief at 24%)
- HMRC: Capital Gains Tax rates and allowances
- GOV.UK: Tax when you sell property – work out your gain
- GOV.UK: Tax when you sell your home – letting out part of your home
- GOV.UK: Capital Gains Tax – gifts to your spouse or civil partner
- HMRC: HS282 Death, personal representatives and legatees
- HMRC: SDLT Manual – deemed market value on transfers to a connected company
- HMRC: Capital Gains Tax summary notes (connected persons and market value)
- GOV.UK: Guide to the Renters’ Rights Act
- GOV.UK: Grounds for possession – guidance for landlords
- GOV.UK: Enforcement measures for landlords
- Bank of England: Bank Rate history
- ONS: Private rent and house prices, UK – October 2026
- HM Land Registry: UK House Price Index data downloads
This article is news and general guidance only, not financial, legal or tax advice. Tax treatment depends on your circumstances and may change.