Rents Hit Record £1,418 – But 5.34% BTL Rates Crush the Maths
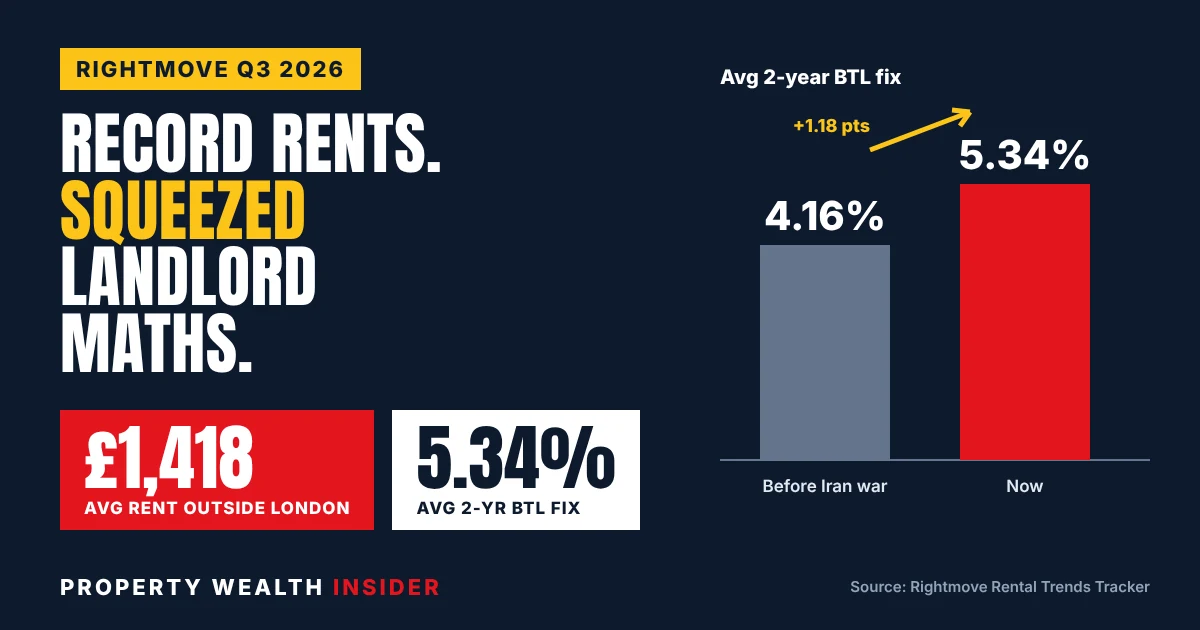
Advertised rents outside London have broken through £1,400 a month for the first time. Rightmove’s Q3 2026 Rental Trends Tracker, released on Thursday 15 October 2026, puts the average at a record £1,418 per calendar month, with London also at a new high of £2,825.
But there is a catch. The same report says the average two-year fixed buy-to-let mortgage rate has climbed to 5.34%, up from 4.16% before the war in Iran started. Record rents do not help much if the mortgage eats the margin and the lender’s rental stress test blocks the loan.
This affects anyone buying a rental, and every landlord whose fixed rate ends in the next year or so. Below we break down the figures, run the numbers on a typical deal and give you a checker so you can test your own.
Key facts
- Average advertised rent outside London: £1,418 pcm, a record and the first time above £1,400 (Q3 2026, Rightmove).
- Annual rent growth outside London is +2.4%, compared with roughly +10% a year between 2021 and 2023.
- London average advertised rent: £2,825 pcm, up 3.2% a year, with available rentals down 9% and tenant demand up 6%.
- Average two-year fixed buy-to-let rate (75% LTV, no fee): 5.34%, against 4.16% before the Iran war began.
- Share of homes to rent that were previously for sale fell from 17% to 15% – Rightmove reads this as reduced landlord investment.
- Bank Rate is 3.75%; the next Bank of England decision is due on 5 November 2026.
What Rightmove’s Q3 figures show
Rightmove’s tracker is built from asking rents on its own portal – 437,652 of them between 1 July and 30 September 2026, with short lets removed. It covers Great Britain (England, Scotland and Wales), not Northern Ireland, and measures advertised rents rather than what tenants finally agree to pay.
The headline “national” figure excludes Greater London, which Rightmove reports separately. Here is how the last five quarters look, taken from Rightmove’s own tracker reports.
| Quarter | GB excl. London (pcm) | Annual change | Greater London (pcm) | Annual change |
|---|---|---|---|---|
| Q3 2025 | £1,385 | +3.1% | £2,736 | +1.6% |
| Q4 2025 | £1,370 | +2.2% | £2,716 | +0.8% |
| Q1 2026 | £1,370 | +1.6% | £2,736 | +1.4% |
| Q2 2026 | £1,397 | +2.3% | £2,791 | +2.9% |
| Q3 2026 | £1,418 | +2.4% | £2,825 | +3.2% |
The takeaway: rents are still rising, but slowly. Rightmove notes annual growth hovered around 10% between 2021 and 2023. Today’s 2.4% outside London is a quarter of that pace, and below the 3.1% CPI inflation the Bank of England reports.
Supply and demand outside the capital are broadly in balance. Available rental homes are 2% lower than a year ago, and tenant demand is also down around 2%.
What about landlords leaving? Rightmove says about 13% of homes for sale were previously rentals, broadly stable this year and only slightly up on 12% last year. The bigger signal is on the way in: the share of rental listings that were previously for sale has fallen from 17% to 15%, which Rightmove reads as reduced landlord investment.
Why London rents are speeding up again
London is the outlier. Total available rental listings are down 9% on a year ago and newly listed homes are down 7%, while tenant demand is up 6%. That gap is why London growth (3.2%) has overtaken the rest of Great Britain.
Inner London now averages £3,349 a month (+4.0%) and outer London £2,442 (+2.5%). Rightmove ranks London third of its regions for annual rent growth, behind cheaper areas with more headroom.
Yields tell the other side of the story. Rightmove’s average landlord yield for Great Britain is 6.6%, but London is the lowest at 6.1%, against 8.3% in the North East and 7.9% in Scotland. High London rents still struggle to cover high London prices once borrowing costs rise.
How 5.34% rates change the cashflow
Rightmove’s rate comes from its daily buy-to-let mortgage tracker: a two-year fix at 75% loan-to-value with no fee. The path this year has been bumpy, all on Rightmove’s own figures.
| Rightmove report | Average 2-year fixed BTL rate |
|---|---|
| Q4 2025 tracker (25% deposit) | 4.84% |
| Before the war in Iran started (as cited in Q3 2026 tracker) | 4.16% |
| Q2 2026 tracker, released 16 July 2026 | 5.55% (down from 5.67% the month before) |
| Q3 2026 tracker, released 15 October 2026 | 5.34% |
Meanwhile the Bank of England held Bank Rate at 3.75% on 17 September 2026, warning that energy prices disrupted by the Middle East conflict could push inflation higher. Buy-to-let fixes price off market expectations, which is why they have risen even with Bank Rate on hold.
Worked example: a £250,000 rental at the record rent
Take a £250,000 home let at £1,418 a month, bought with a 25% deposit. That is a £187,500 interest-only loan and a gross yield of 6.81%. Allow 15% of rent (£213) for letting fees, repairs, insurance and voids.
| Per month | At 4.16% (pre-war) | At 5.34% (now) |
|---|---|---|
| Rent | £1,418 | £1,418 |
| Mortgage interest | £650 | £834 |
| Running costs (15%) | £213 | £213 |
| Cashflow before tax | £555 | £371 |
The rate rise costs £184 a month, or about £2,213 a year – a third of the pre-tax profit gone. To claw that back through rent alone you would need roughly a 13% rent rise, against market growth of 2.4%.
Tax makes it worse for individual landlords. Under the Section 24 rules, mortgage interest is not deducted from rental profit; instead you get a tax credit at the basic rate of 20%. Using 2026-27 rates for England, Wales and Northern Ireland, and assuming all the profit falls in one band:
- Basic-rate taxpayer: about £890 a year in tax, leaving roughly £297 a month.
- Higher-rate taxpayer: about £3,783 a year, leaving roughly £56 a month.
- Additional-rate taxpayer: about £4,506 a year, leaving a small monthly loss.
From 6 April 2027 the government has confirmed separate property income rates of 22%, 42% and 47% in England, Wales and Northern Ireland, with finance-cost relief given at 22%. Scotland will set its own approach. Factor that into any deal you hold beyond this tax year.
The remortgage shock for existing landlords
Rightmove’s mortgage expert flags that many landlords are still coming off cheaper fixes. As an illustration only: a £150,000 interest-only loan moving from a 2% fix to 5.34% goes from £250 to £668 a month. That extra £418 a month is £5,010 a year that the rent has to find.
The lender stress test that can kill a deal
Cashflow is only half the battle. Lenders regulated by the Prudential Regulation Authority must run an interest coverage ratio (ICR) test: the rent has to cover the mortgage interest by a set margin, calculated at a stressed rate rather than your actual rate.
The PRA’s supervisory statement SS13/16 says lenders should assume rates rise by at least 2 percentage points, with a floor of 5.5%, unless the rate is fixed for five years or more. It describes 125% as the industry-standard minimum ICR. Many lenders use 125% for limited companies and basic-rate taxpayers and around 145% for higher-rate taxpayers – but criteria vary, so treat these as typical, not universal.
Back to our £187,500 loan at £1,418 rent. Here is the minimum rent each test demands:
| Scenario | Stress rate | ICR | Rent needed | Max loan at £1,418 |
|---|---|---|---|---|
| 2-yr fix at 4.16%, basic rate / company | 6.16% | 125% | £1,203 | £220,987 |
| 2-yr fix at 5.34%, basic rate / company | 7.34% | 125% | £1,434 | £185,460 |
| 2-yr fix at 5.34%, higher rate | 7.34% | 145% | £1,663 | £159,880 |
| 5-yr fix (rate below 5.5%), basic rate / company | 5.50% | 125% | £1,074 | £247,505 |
| 5-yr fix (rate below 5.5%), higher rate | 5.50% | 145% | £1,246 | £213,367 |
On a two-year fix, the jump from 4.16% to 5.34% lifts the rent needed to pass from about £1,203 to £1,434. At today’s record £1,418 rent, the 75% loan fails by around £16 a month. A higher-rate taxpayer would be capped at about £160,000 – a deposit of £90,000 rather than £62,500.
That is why five-year fixes, limited company structures and larger deposits are so common right now. They are ways of passing the stress test, not just of cutting the monthly bill.
Buy-to-let deal checker
Plug in your own deal. The rate defaults to Rightmove’s 5.34% two-year average; change it to your actual quote.
Buy-to-let deal checker
Guide only, not financial or tax advice. Stress test is illustrative: ICR 125% (company/basic rate) or 145% (higher/additional rate), at your rate plus 2 points (minimum 5.5%) for fixes under five years, or the higher of your rate and 5.5% for five-year fixes. Lenders’ criteria vary. After-tax figure uses 2026-27 rates for England, Wales and NI, assumes all profit is taxed at the band chosen with a 20% finance-cost credit, and is not shown for companies (corporation tax not modelled).
What to do now
If you are buying
- Price the rent from comparable live listings, not the regional headline. Lenders will want a valuer’s rent figure.
- Run the stress test before you offer. If the rent fails, decide now whether you will add deposit, take a five-year fix or walk away.
- Compare two-year and five-year fixes on stress test outcome as well as monthly cost.
- Model your after-tax position, including the 22%/42%/47% property income rates from April 2027 if you are an individual in England, Wales or Northern Ireland.
- Talk to a specialist broker and, if a company structure is on the table, an accountant before you buy – not after.
If your fix is ending
- Note the end date and start comparing deals well before it, so you are not pushed onto your lender’s standard variable rate.
- Get a product transfer quote from your current lender and compare it with the wider market through a broker.
- Plan any rent review around the new payment, remembering Rightmove’s point that reviews are now generally limited to once a year.
- If the numbers no longer work, compare holding, reducing the loan, or selling, with tax advice on capital gains.
- Local comparable rents checked (at least three live listings)
- Gross yield calculated on realistic rent
- Cashflow tested at today’s rate and at rate plus 2 points
- Lender ICR and stress rate confirmed with broker
- After-tax profit modelled for 2026-27 and 2027-28
- Running costs budgeted (fees, repairs, insurance, voids, compliance)
- Fix end dates on existing loans in your diary
- Exit plan if rates stay high
FAQ
What is the average rent in the UK right now?
Rightmove’s Q3 2026 figures put the average advertised rent across Great Britain outside London at £1,418 a month and Greater London at £2,825. These are asking rents on new listings, not rents paid by existing tenants, and do not cover Northern Ireland.
What is the average buy-to-let mortgage rate today?
Rightmove’s daily tracker shows an average two-year fixed buy-to-let rate of 5.34% at 75% LTV with no fee, as of its 15 October 2026 report. Your rate will depend on deposit, fees, lender and whether you buy personally or through a company.
How much rent do I need for a buy-to-let mortgage?
Multiply the loan by the lender’s stress rate and its ICR, then divide by 12. A £187,500 loan stressed at 7.34% with a 125% ICR needs about £1,434 a month. Use the checker above for your figures.
Is buy-to-let still worth it in 2026?
It depends on the deal. Higher-yield areas – Rightmove puts the North East at 8.3% and Scotland at 7.9% – can still work at current rates, while low-yield, highly geared purchases may struggle to cashflow or pass lender tests, especially for higher-rate taxpayers.
Will buy-to-let mortgage rates come down?
Nobody knows. Rightmove’s average has eased from 5.55% in July to 5.34%, but the Bank of England has warned it may need to raise Bank Rate if high energy prices feed into inflation. The next decision is due on 5 November 2026.
Sources
- Rightmove Rental Trends Tracker Q3 2026 (released 15 October 2026)
- Rightmove Rental Trends Tracker Q2 2026
- Rightmove Rental Trends Tracker Q4 2025
- Bank of England – Interest rates and Bank Rate
- PRA Supervisory Statement SS13/16 – buy-to-let underwriting standards
- GOV.UK – Income Tax rates and bands
- GOV.UK – Changes to tax relief for residential landlords
- GOV.UK – Changes to tax rates for property, savings and dividend income
This article is news and general guidance only. It is not financial, legal or tax advice.